All Categories
Featured
Table of Contents
If you desire to repair your own credit: Visit to download complimentary copies of your credit reports from all 3 major credit bureaus, which you can do as soon as a week. Make sure to review your reports for any possible indications of credit errors or fraud. Send conflicts to report unreliable or deceitful info on your credit report.
How Expert Financial Guidance Improves a ScoreIf you have supporting documents to back up your claims, include it with your disagreement to enhance your odds of an effective examination. Payment history is the most crucial consider your credit history worth 35% of your FICO Score and 41% of your VantageScore credit history. Paying on time won't technically repair your credit, but it can help you prevent brand-new credit report damage that could set back your effort.
Plus, lowering credit card financial obligation has the included advantage of saving you money in interest charges. While you do not need to be scared to use for brand-new credit accounts in an accountable way, it's crucial to prevent letting lending institutions or credit card business inspect your credit report excessively.
Monitoring your credit can assist keep you encouraged throughout the credit repair procedure and might inform you if any brand-new negative information appears on your credit report. Credit repair work companies provide to manage the credit repair procedure in your place. Essentially, you're working with a 3rd party to perform a service that you prefer not to do on your own.
Typically, a credit repair company starts by getting copies of your credit reports. Next, they recognize possible concerns and disagreement mistakes with the credit bureaus (and perhaps creditors also) in your place. Lots of companies will follow up with additional disagreements if the very first attempt is not successful. And some credit repair work business may provide financial obligation validation or lender negotiation services as well.
How Expert Financial Guidance Improves a Score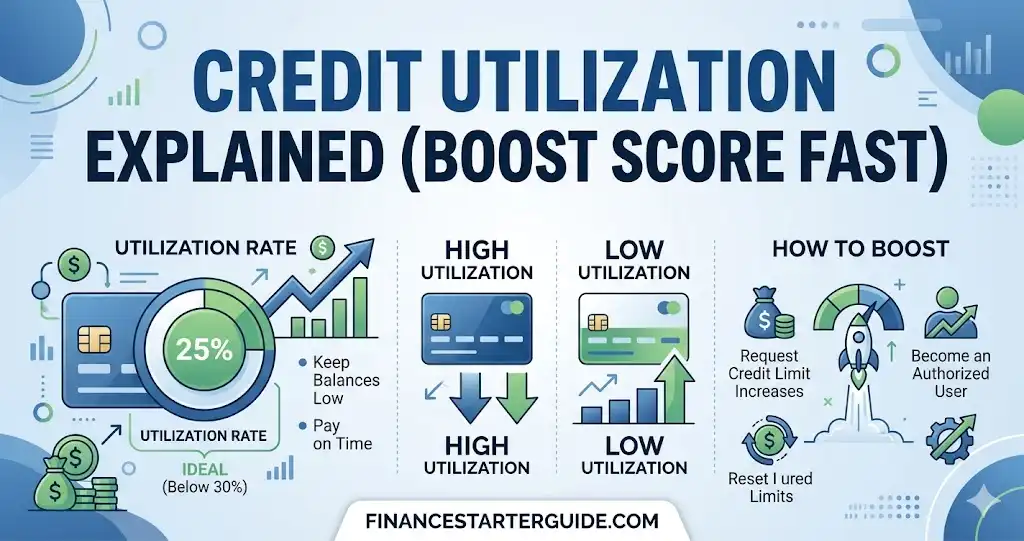
Your Consumer Rights Under 2026 Credit Laws
Costs vary, but many companies charge a setup fee (typically $70 to $200) and a month-to-month service fee varying from $50 to $150. It's likewise crucial to understand that some companies restrict the number of disputes they send to the credit bureaus in your place per billing period. The purpose of limited disputes is to slow down the conflict procedure and extend the number of months a client stays in the credit repair work program, paying a regular monthly fee.
It's also essential to handle your expectations. Whether you hire a credit repair business or send credit conflicts yourself, there is no assurance that accurate, negative details will be removed from your credit report right away. The credit bureaus can leave most unfavorable products on your credit report for approximately seven years (ten years for certain personal bankruptcies) unless there's an error.
Guarantees to remove accurate info from your credit report Needs for upfront payment before finishing services No written contract An agreement that doesn't include a cancellation policy Any claims of helping you produce a "new credit identity" Encouraging you to lie (like making incorrect claims that you're a victim of identity theft) The Credit Repair Organizations Act (CROA) secures consumers from credit repair work frauds.
Budgeting and Financial Counseling Strategies
If you decide to employ a credit repair business, it's important to do your research to make sure you discover a trustworthy option. Whether you receive a recommendation or find a credit repair business online, do some fundamental research study.
You can likewise look for complaints on the CFPB complaint database. Any legitimate credit repair work company will follow CROA standards including supplying agreements, providing customers the right to cancel, not requiring advance payment without services and not presenting misleading information. It's also important to look around and compare services from several credit repair business before you decide.
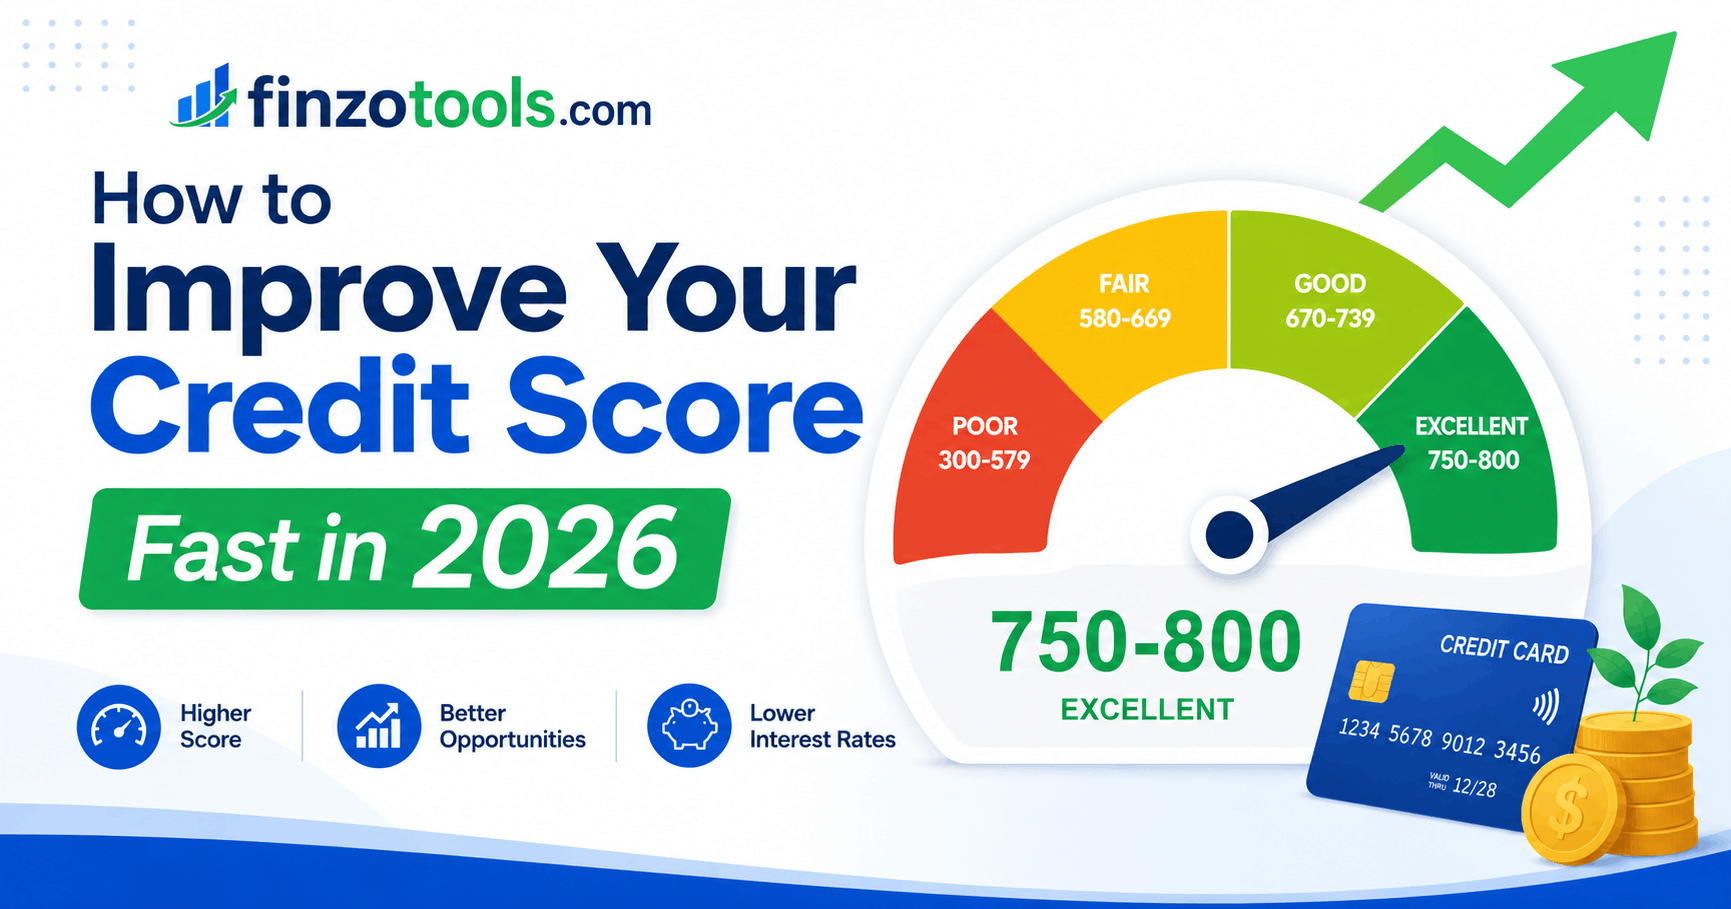
Both DIY credit repair work and credit repair work companies can just help in specific circumstances. In a lot of cases, other methods may be a better fit, particularly if your low credit rating is due to high debt, missed payments or other accurate but unfavorable credit information that is going to stay on your credit reports for the foreseeable future.
It might stay on your credit reports for up to 10 years, and the credit rating effect can be substantial. Negative items fall off your credit report over time (7 to 10 years in a lot of cases).

Latest Posts
The Advantages of Professional Financial Counseling Services
Comparing Professional Services and DIY Repair
Essential Financial Literacy in 2026