All Categories
Featured
Table of Contents
This may appear counterproductive: Undoubtedly more credit suggests more money to spend and, for that reason, more danger? While that's real on the surface, keep in mind that your credit usage ratio makes up almost a third of your FICO rating (and is likewise an essential part of your VantageScore). That's why getting to extra credit can enhance your credit history.
A Guide to Debt for Young SpecialistsA new credit card or a broadened credit limit could increase your credit score. Let's state you have a single credit card with a limit of $5,000.
Or, possibly you apply for a new card and are provided a $5,000 line. With this one action, you've just increased your offered credit to $10,000.
This only works if you do not utilize the new credit line to invest beyond your means. As long as your spending remains consistent, you're just spreading out that quantity out over a bigger credit limitation, dropping your usage and increasing your score. Credit cards are not always a proven way to get into debt; make certain you keep your purchases in line with your earnings.

Key Financial Literacy for Adults for 2026
As noted above, your payment history is the most crucial factor in determining your credit report, and even a single late payment can drastically reduce your score, as it shows that you might be struggling to.By setting up reminders or making it possible for automatic payments from your checking account, you guarantee that every payment will be processed on or before your statement due date.
AMERICAN EXPRESSOf course, this includes the caution that you must preserve enough cash in your savings account to cover the balance that will be paid immediately. Otherwise, the overdraft cost could consume away at your revenues and still lead to a late payment. Our No. 1 here at TPG is: Thou shalt pay thy balance in complete.
A basic budget plan is vital if you're trying to pay down a credit card debt. D3SIGN/GETTY IMAGESHowever, you might have an old debt from your freewheeling days as an university student, or perhaps you elected to fund a big purchase with an or deferred interest offer on an installment plan card.
If you have not already done so, sit down and create a spending plan for how you'll pay these balances off to avoid (or decrease) your interest exposure. This last idea will not always lead to an instant increase in your credit report. Still, it's a finest practice to keep tabs on your score and quickly identify any issues that might emerge.
Services like Credit Karma can alert you of credit rating modifications. CREDIT KARMAWe like to utilize Credit Karma, a free service that tracks your TransUnion and Equifax ratings and allows you to see your credit report whenever you desire. You can also set informs for various things, such as changes to your report.
Evaluating Credit Repair and Counseling Methods
This will increase your approval odds for leading travel rewards credit cards, broaden your access to installment loans and even lower the rate of interest and charges you 'd pay to loan providers. If you have actually made a resolution to increase your scores in 2026, we hope this guide has actually provided you some concrete steps to improve your credit health in the coming weeks and months.
How Does LendingTree Get Paid? We are committed to offering accurate material that helps you make notified cash decisions.
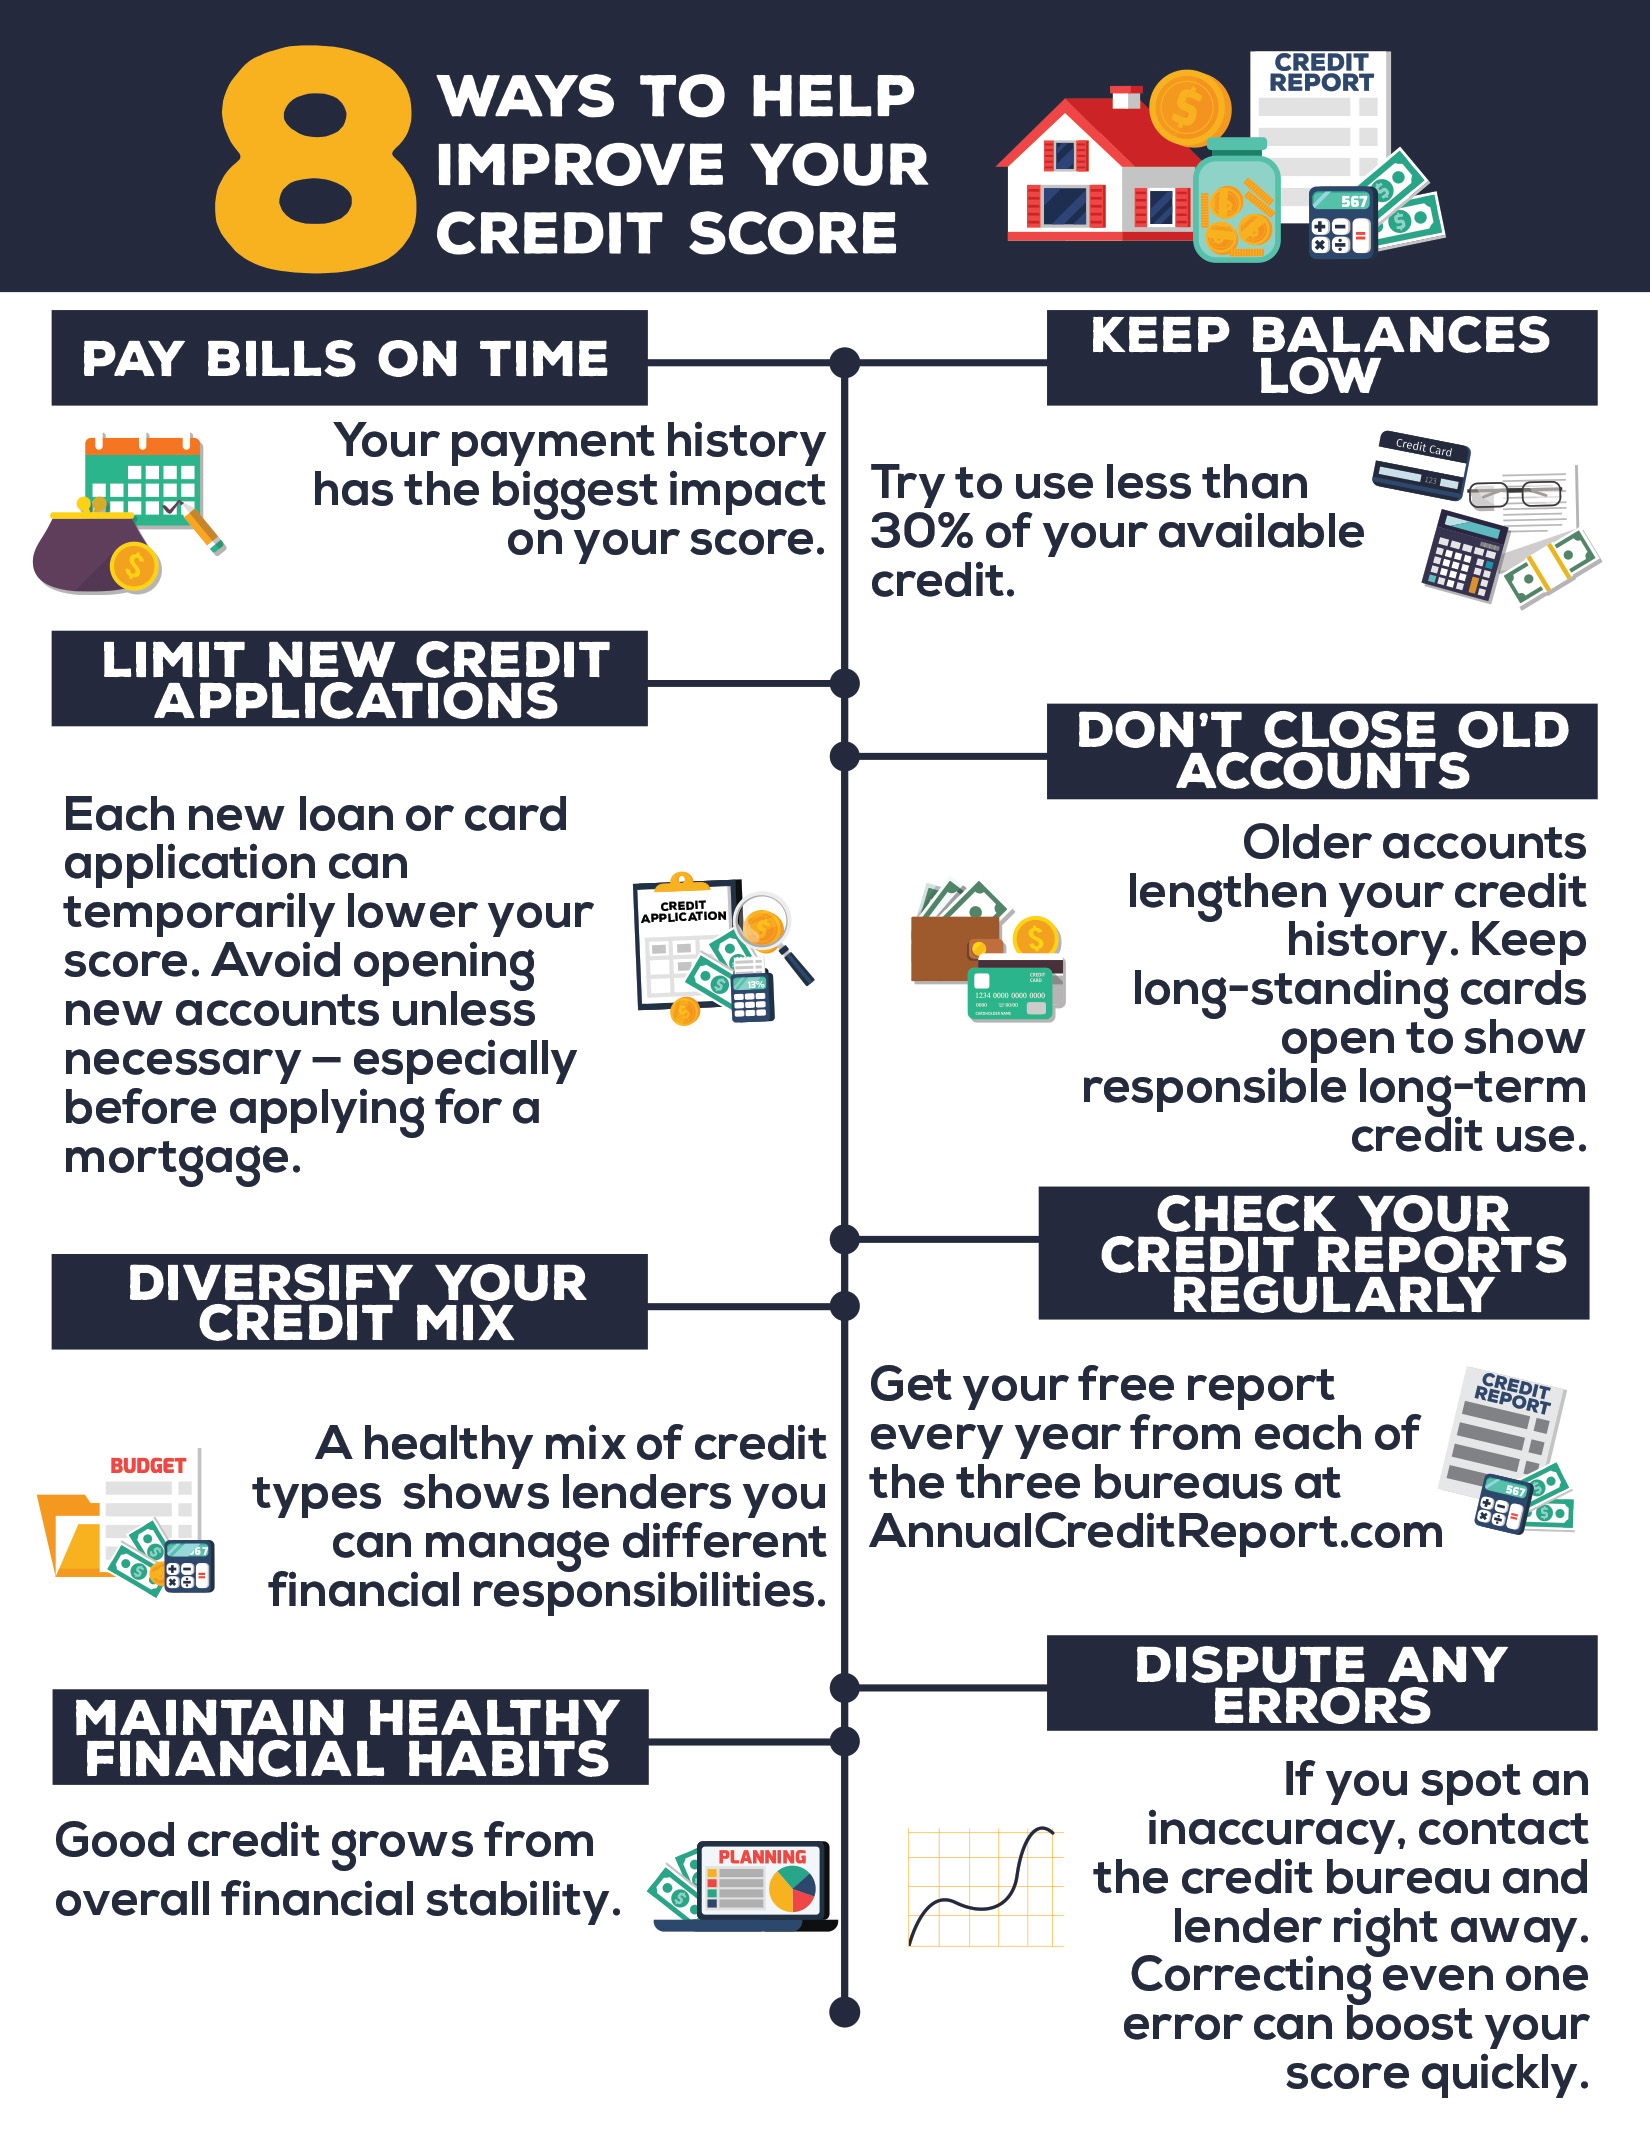
There are numerous proven ways to enhance your credit rating. The ideal method depends on what's in your credit report, however the 11 strategies listed below cover the most efficient relocations you can make., and challenging them can have a quick effect. Conserve your money challenging mistakes yourself is totally free and just as reliable.
Your Consumer Rights in 2026 Credit Repair
Results vary depending upon the number of missed out on payments you have and how far overdue they are. Missed out on payments remain on your report for 7 years, however their effect fades in time. Your credit utilization ratio, the quantity of credit you're using versus what's available, represent 30% of your FICO Score and 20% of your VantageScore.
If yours is higher, paying down financial obligation is one of the fastest methods to improve your score. Consider utilizing the debt snowball or financial obligation avalanche method to pay it down without otherwise affecting your score. Within a month of your new utilization ratio being reported to the credit bureaus. That card's credit limitation and history get factored into your own rating.
As an authorized user, the main cardholder's behavior affects your credit too. If they miss payments or bring a high balance, it can harm your rating, not just theirs. As quickly as the card provider reports the brand-new account to the bureaus in some cases within a billing cycle or 2. Once it's approved and reported, it can decrease your credit utilization and enhance your credit score.
Your Consumer Rights in 2026 Credit Laws
Ask your issuer whether a tough inquiry is needed first, as that can temporarily lower your score. Quick once the greater limitation is reported to the bureaus, your utilization ratio drops and your rating ought to follow.
You can likewise dispute the info if it's inaccurate or too old to be listed. FICO 8, the most commonly used variation, counts paid and unpaid collections on financial obligations of $100 or more. More recent designs, FICO 9 and 10, neglect paid collections entirely and treat unpaid medical collections less significantly.
Get customized debt relief solutions that may lower what you owe and help you gain back financial stability. These cards are backed by a money deposit (normally paid in advance), which serves as your credit line. They work like a regular credit card and report your payment history to the bureaus the same way, so constant on-time payments build your score gradually.
Navigating Credit Repair Laws in 2026
Not all scoring designs element in this information, however where it's considered, a constant record of on-time payments can meaningfully improve your score. As soon as the information is reported to the bureaus.

Latest Posts
The Advantages of Professional Financial Counseling Services
Comparing Professional Services and DIY Repair
Essential Financial Literacy in 2026